Weekly Market Update 9/17/2026
|
|

Here is your weekly market update from the Garden City Co-op Grain Origination Team.
Trivia
-
How many season's are in a year?
-
What is James Bond code name?
Answers at the bottom.
Market News
CORN BALANCE SHEET RECAP: FWIW, After Friday’s report and taking a quick look at updated WCB corn balance sheets using the USDA’s "super accurate" yield estimates. State balance sheets are a bit like recreating the Mona Lisa with crayons.
-
I'm working off IMPLIED ending stocks from the June Stocks report, which will likely change after the September Stocks report. We'll need to reevaluate once those numbers are available.
-
Production is projected to decline roughly 19% in ND, 22% in SD, 17% in NE, and 16% in KS.
-
For demand, I used the 10-year average for Nebraska and the second-highest demand year of the last decade for ND, SD, and KS (only trailing last year). Nebraska's biggest demand decline appears likely in the western part of the state, while eastern Nebraska continues to hold inventory.
-
If you exclude last year's record (or record-on-paper) production, the 6-year average carryout is approximately:
-
ND: 43.6 million bu
-
SD: 82.8 million bu
-
NE: 142.2 million bu
-
KS: 58.6 million bu
-
Using lower production estimates, last year's record carryout, and the demand assumptions above, the combined WCB carryout still comes in roughly 16 million bushels above the 6-year average.
I fully understand that with state-by-state balance sheets, 16 million bushels can easily become a rounding error, and the September Stocks report will likely reshuffle these numbers, but I wanted to see how "bad" the 2026 WCB balance sheet looked on paper. Based on these penciled-in assumptions, the numbers do not suggest a runaway bullish supply situation heading into this marketing year.
NOPA CRUSH REPORT: Compared with recent crush trends, the August NOPA crush figure of 205.5 million bushels stands out as a notable slowdown. Month-over-month August declined more than 11 million bushels from July, reversing the strong pace seen through the marketing year. Cumulative crush remains historically strong. NOPA members have crushed roughly 2.580 billion bushels through the first 11 months of 2025/26, still running about 12% above last year due to expanded processing capacity and renewable fuel demand. The USDA's crush pace through July was closer to an 8.4% year-over-year increase, which is much more in line with the agency's current annual crush forecast. One disappointing month doesn't signal a major demand problem, but it does suggest that crushers are not operating at the breakneck pace needed to comfortably reach USDA's current 2.655-billion-bushel forecast. August was a clear negative surprise versus both trade expectations and the recent trend of record-breaking crush volumes. However, crush demand remains historically robust overall, and the data points more toward a modest cooling of growth rather than a collapse in soybean demand. If September crush is also underwhelming, USDA could trim crush demand slightly in upcoming WASDE reports.
INTEREST RATE MARKET UPDATE:As expected from last week, the FED hiked rates .25% for the first time in over 3 years, moving the Fed Funds rate to about 3.90%. Expectations are high for at least one more hike before the end of the year. The FED, as a consensus, feels that overall conditions aren’t doing enough to slow the economy. Chairman Warsh noted that this is a “dose of accommodation,” so future hikes depend on the inflation story. The total number of “doses” wasn’t specified, but the FED will continue to raise rates until inflation numbers show enough improvement to warrant a stop.
EXPORT SALES AND INSPECTIONS: Corn export sales totaled 40.4 million bushels this week, in line with current week trade estimates. Current week corn export inspections totaled 60.1 million bushels, down 5.8 million bushels from the week prior. Soybean sales were reported at 62.5 million bushels this week. Soybean export inspections for the week were reported at 24.7 million bushels – landing above the running 10-week average and above current week trade estimates. All wheat export sales totaled 12.0 million bushels this week. Current week wheat export inspections totaled 16.8 million bushels – landing on the upper-end of current trade estimates. Old crop milo export sales were reported this week at 0.2 million bushels and export inspections were reported at 0.1 million bushels.
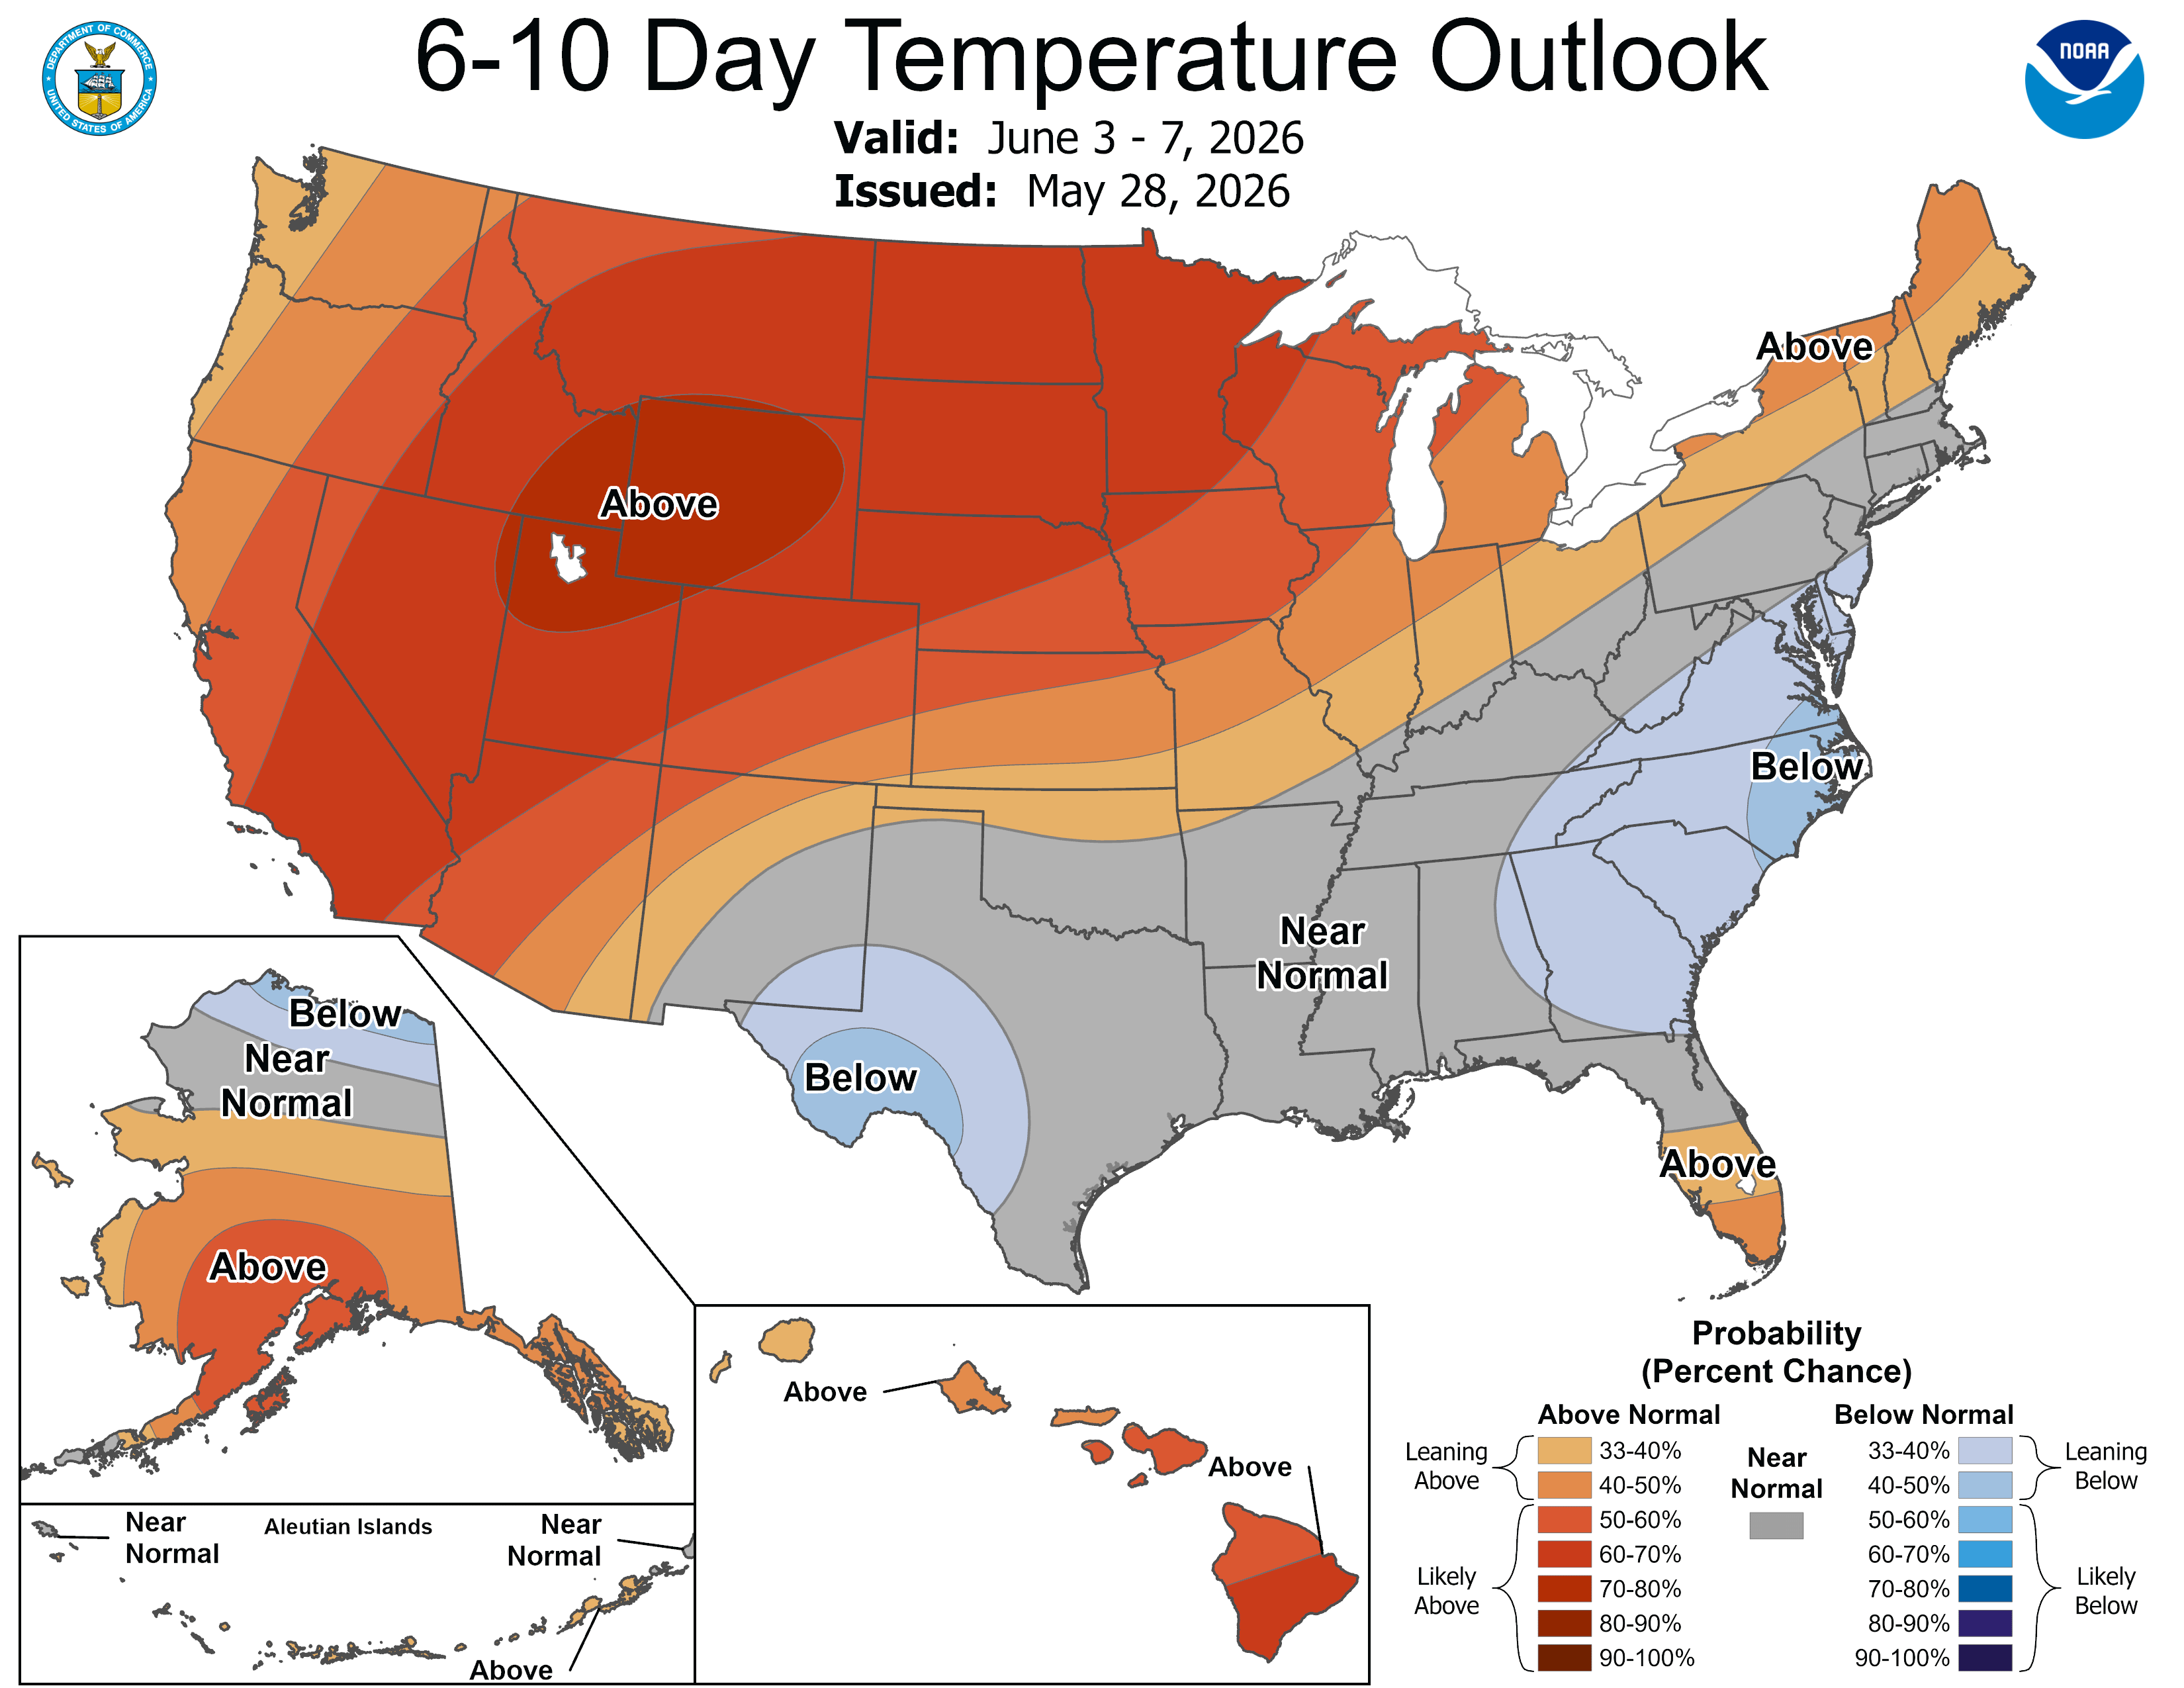
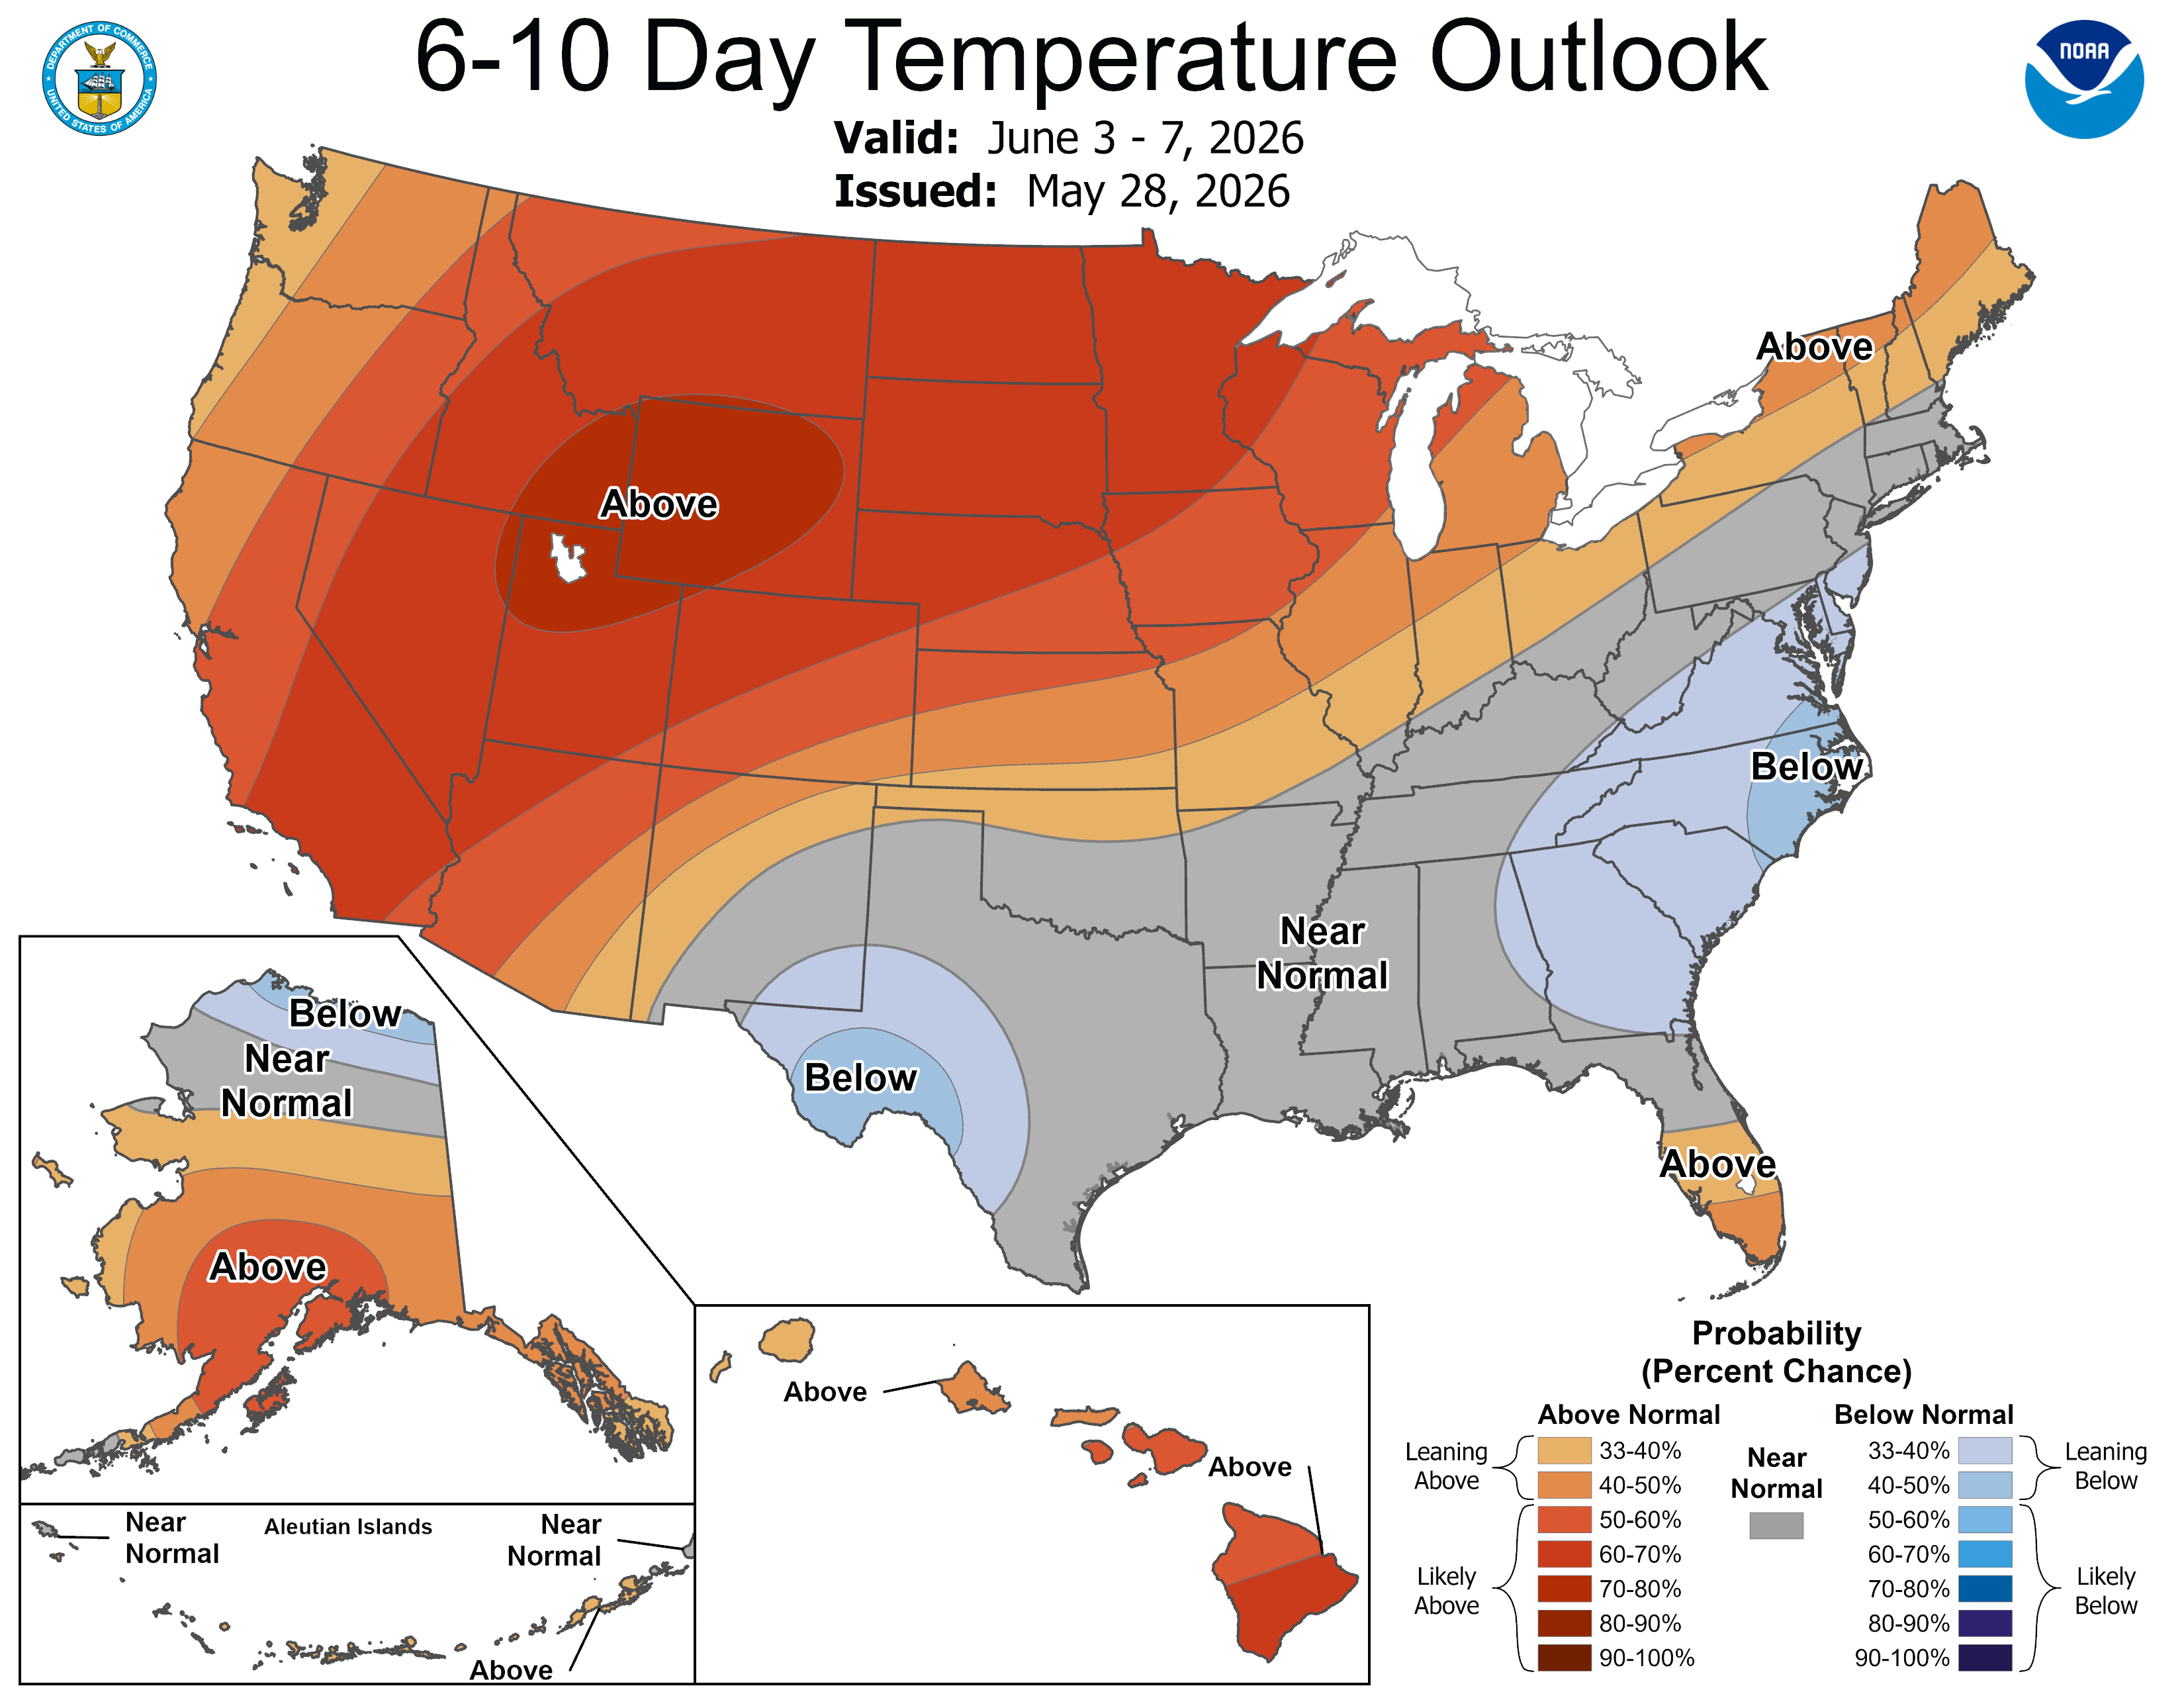
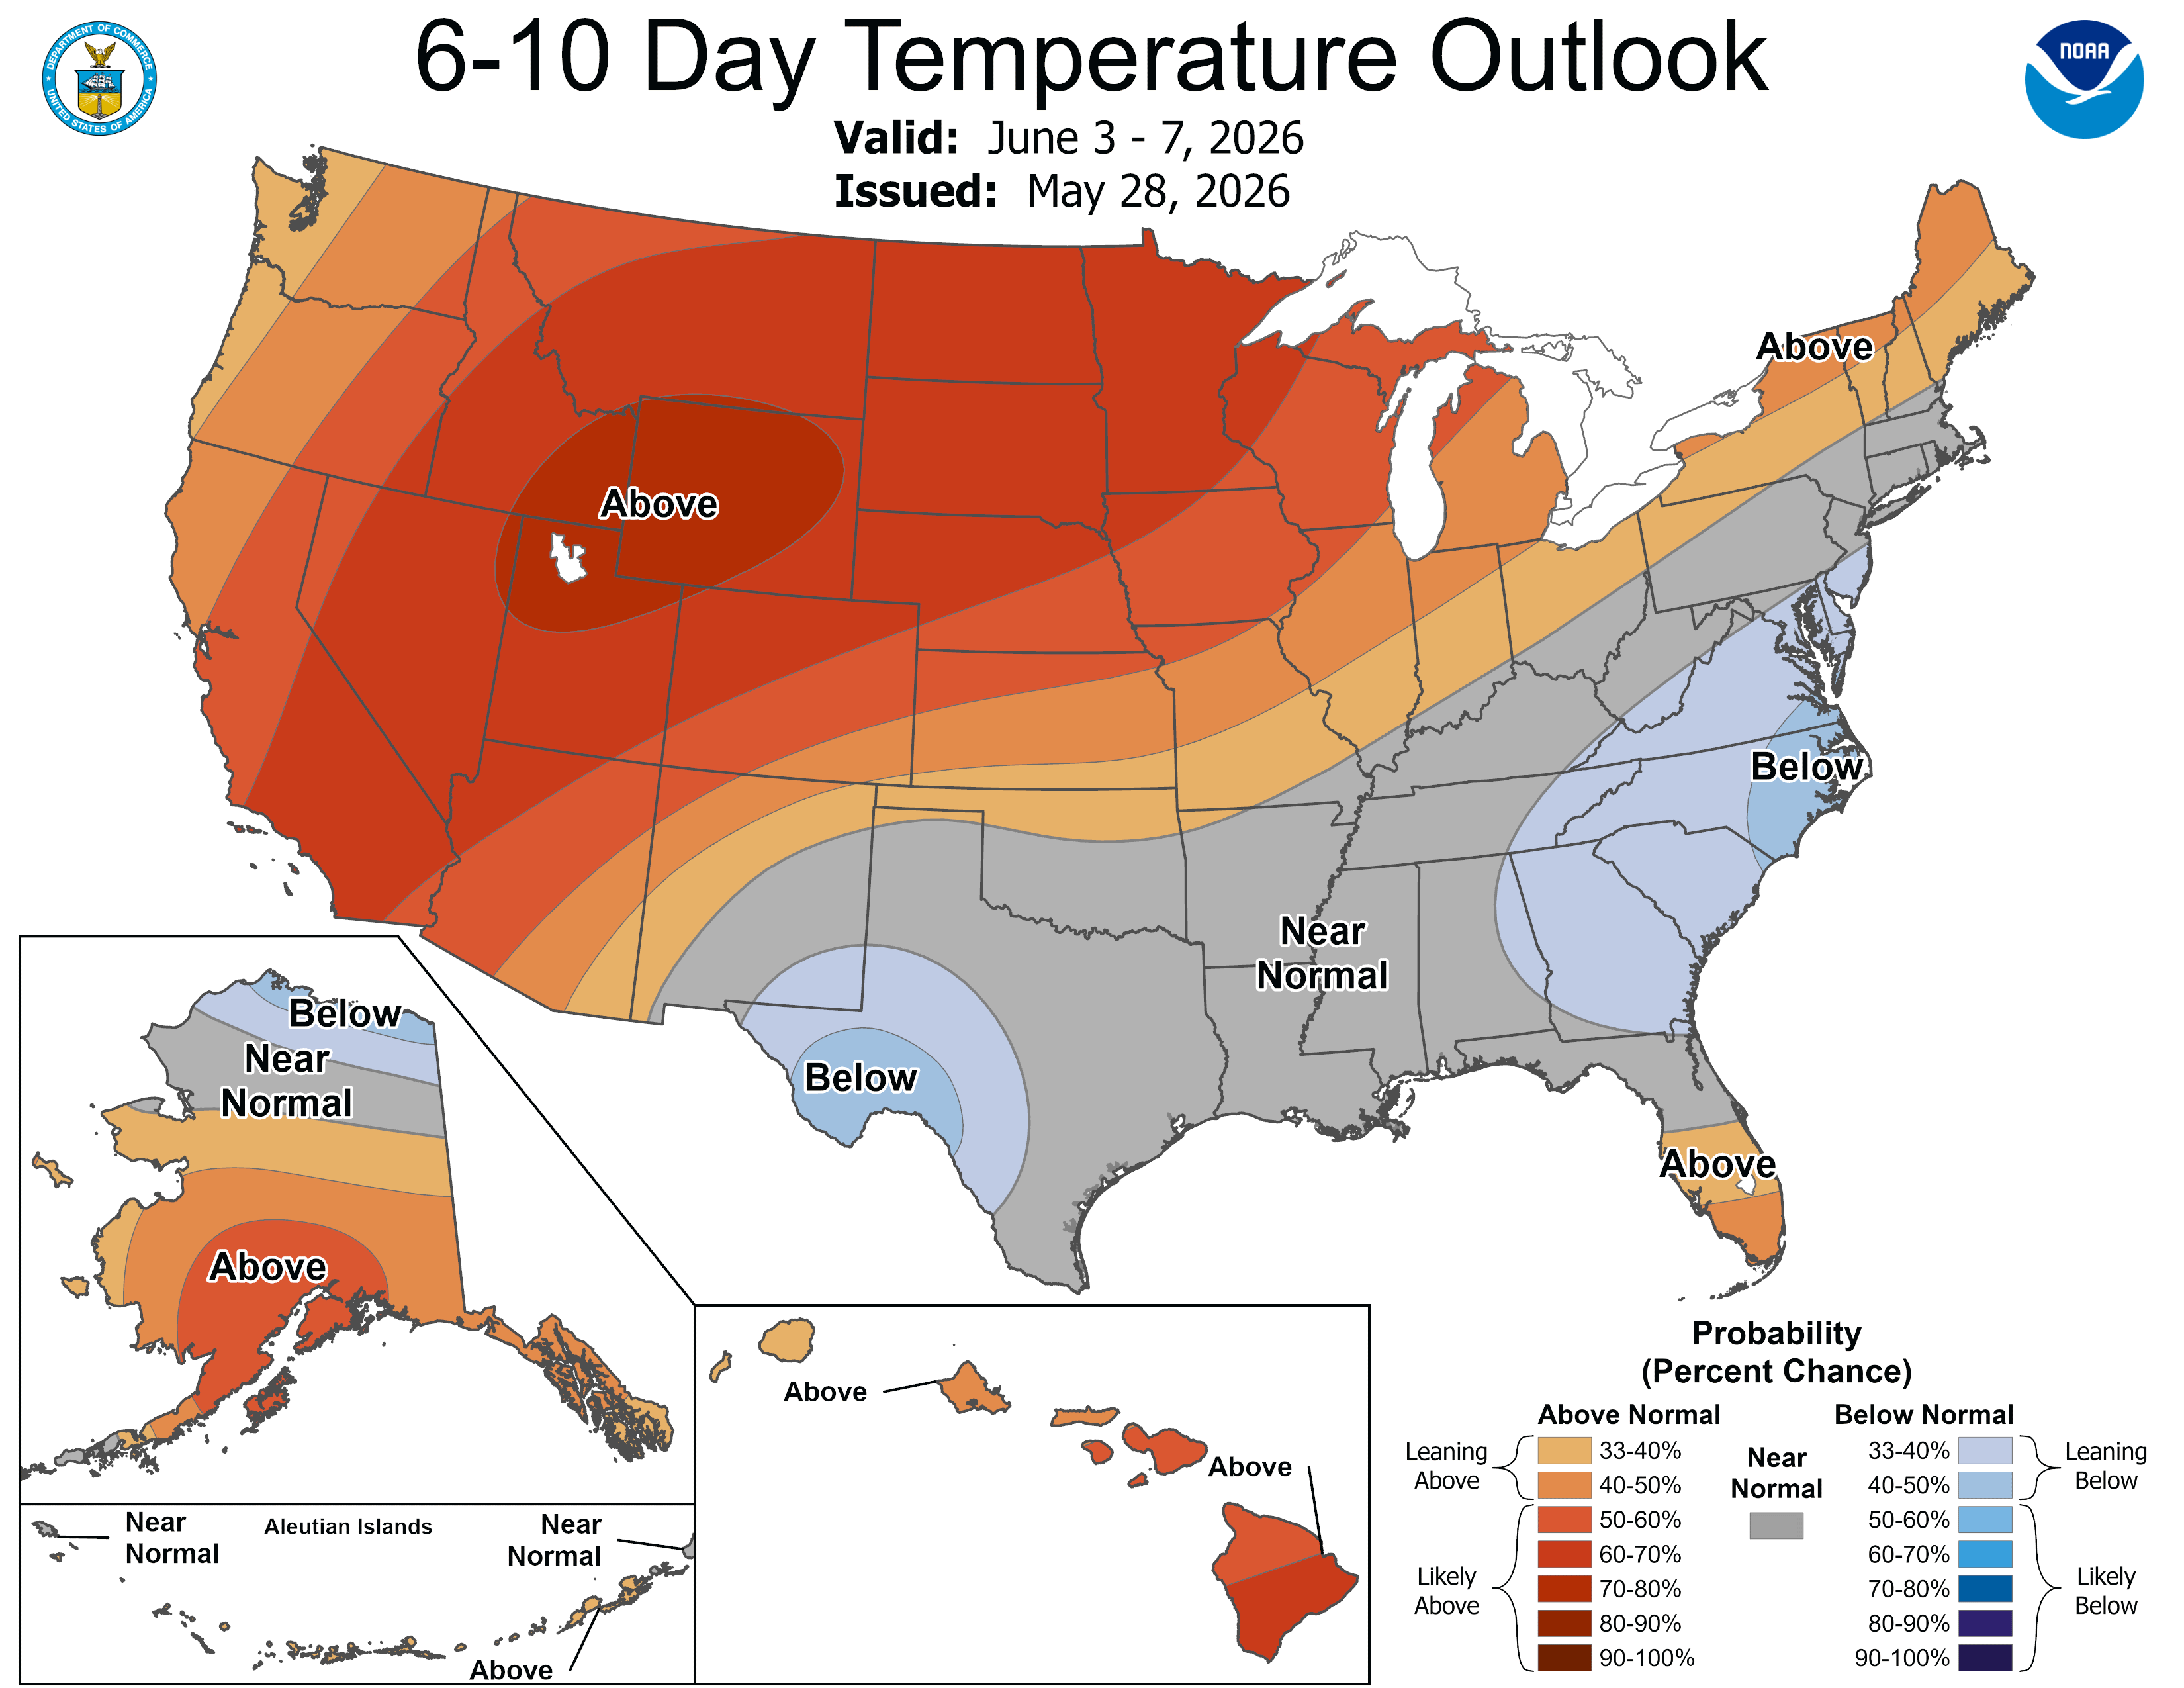
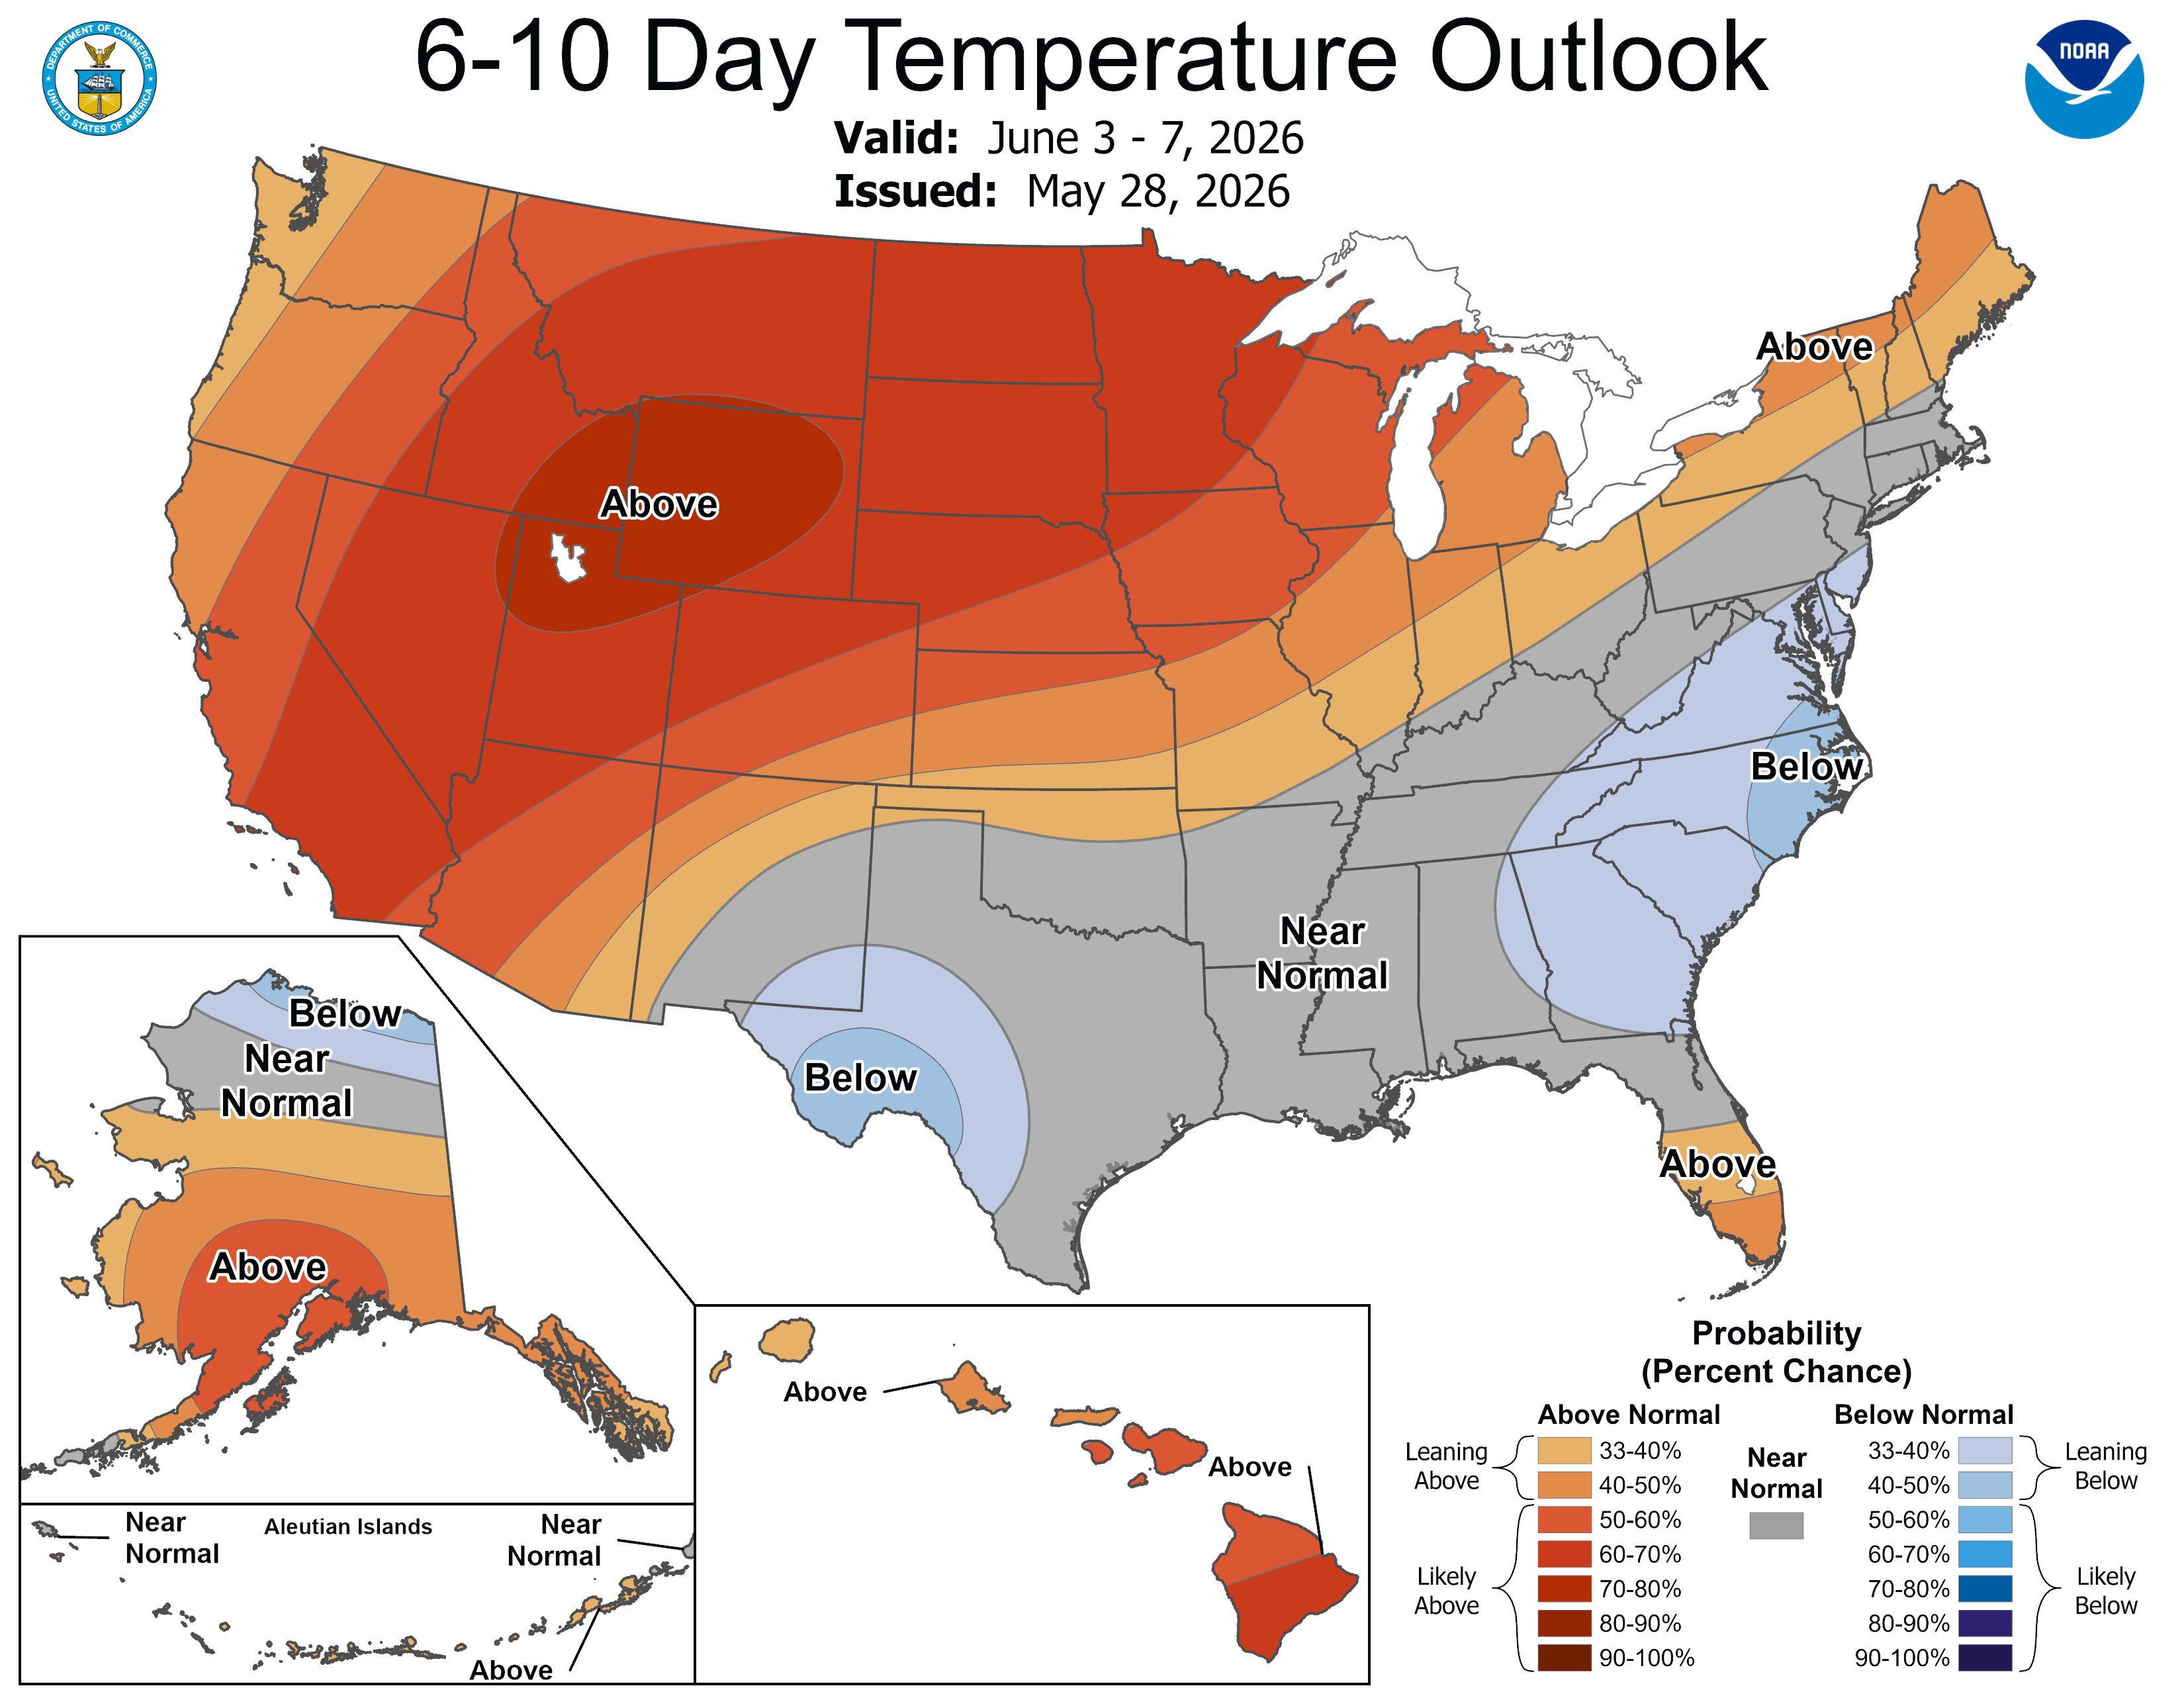
WEATHER: Sunny and hot is the story to again to finish out the work week. Highs today and tomorrow are near 94°F and breezy with overnight lows near 70°F. Rain chances are back Friday night with a 20% chance of thunderstorms. Saturday will be sunny with a high of 91°F with a 70% chance of showers and thunderstorms after 1am. Current estimates are between a tenth and a quarter inch. Sunday will be much cooler and cloudy with highs near 77°F and rainy. Highs next week look to be around 80°F with 40% chances of showers and thunderstorms through Wednesday.
|
|
|
Trivia Answers
-
Four
- 007